
Spending a few months in the United States can change your tax life more than you expect. A work assignment, a study program, or a long family visit can all push you across a line the IRS draws with simple arithmetic. Cross it, and the US may tax your income from anywhere in the world.
This guide explains US tax residency in 2026 in plain language. You'll learn how the Substantial Presence Test works, how to calculate your days step by step, which days you can exclude, and which forms protect your status. You'll also see worked examples, a record-keeping checklist, and the mistakes that trigger most problems.
How Does the IRS Decide US Tax Residency?
The IRS generally treats you as a US tax resident if you meet either of two tests:
- Green Card Test: you were a lawful permanent resident at any time during 2026.
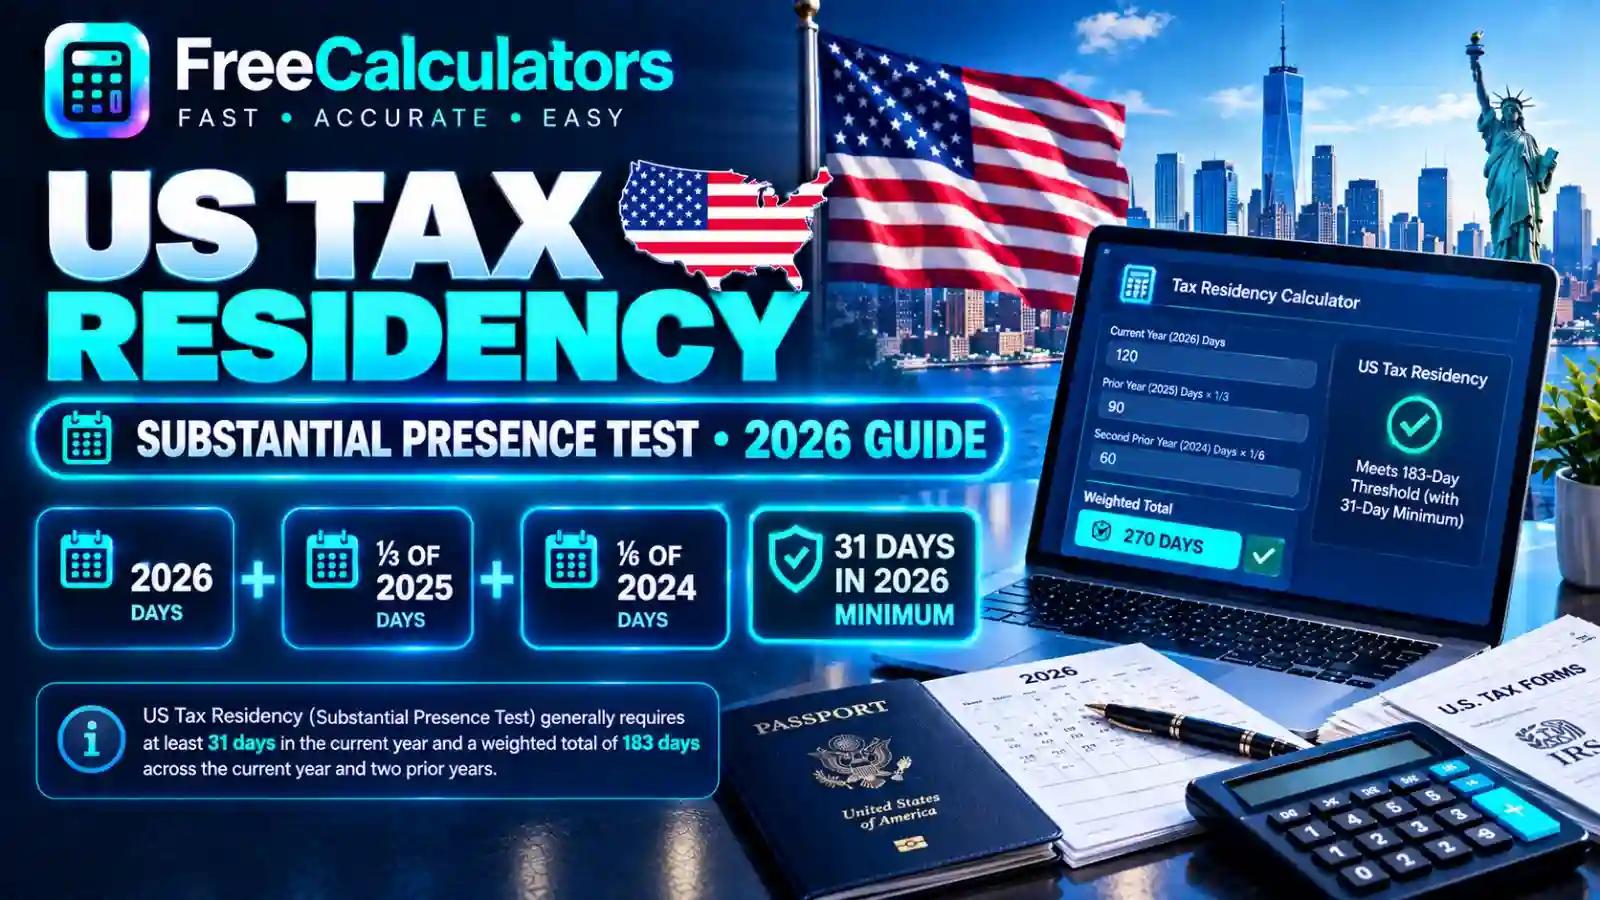
- Substantial Presence Test: you were physically present in the US for at least 31 days in 2026, and your weighted total across three years reaches 183 days.
The weighted formula is:
All eligible days in 2026 + one-third of eligible days in 2025 + one-sixth of eligible days in 2024 = 183 or more
Both conditions must be met. Exempt-individual days, medical-condition days, and a few other categories do not count. The IRS Substantial Presence Test page is the primary source for these rules.
What Is US Tax Residency?
US tax residency is a tax classification. It decides how the Internal Revenue Service taxes you. It has nothing to do with whether you hold a visa, a green card, or citizenship.
That distinction trips people up. You can be a tax resident without a green card, and you can hold a green card and still file under special treaty rules. The IRS explains the framework in its guide to determining an individual's tax residency status.
The statute behind it is Internal Revenue Code Section 7701(b). IRS Publication 519, the US Tax Guide for Aliens, turns that statute into practical guidance.
Resident Alien vs Nonresident Alien
For tax purposes, anyone who is not a US citizen is an "alien." Aliens fall into two groups.
| Feature | Resident Alien | Nonresident Alien |
|---|---|---|
| How you qualify | Green Card Test or Substantial Presence Test | You meet neither test |
| Income taxed | Worldwide income | Mainly US-source income |
| Main return | Form 1040 | Form 1040-NR |
| Tax rates | Same graduated rates as citizens | Graduated rates on business income; flat 30% (or a lower treaty rate) on certain passive US income |
| Deductions | Standard or itemized | Much more limited |
Resident aliens file like US citizens. Nonresident aliens follow a separate, narrower system. If you are unsure which side you're on, the day count settles most cases.
Tax Residency vs Immigration Status vs Citizenship
These three concepts are separate:
- Citizenship is a legal nationality. Citizens are taxed on worldwide income wherever they live.
- Immigration status is your permission to be in the US, governed by USCIS and the US Department of State.
- Tax residency is an IRS classification based on days and legal status.
An H-1B worker who stays long enough becomes a resident alien for tax purposes. An F-1 student on a long program may stay a nonresident for years. The visa category influences your result, but it never decides it alone.
Why US Tax Residency Matters in 2026
The classification changes three things: what the IRS taxes, which return you file, and what you owe in penalties if you get it wrong.
- Taxable scope: Residents report worldwide income, including wages from a foreign employer, rental income abroad, and foreign investment returns. Nonresidents generally report only US-source income. The US worldwide income vs US-source income distinction shapes your entire bill.
- Filing obligations: Residents file Form 1040. Nonresidents file Form 1040-NR, and many must also file Form 8843 even with no income.
- Penalties: Filing the wrong return, or skipping a required form, can leave your return incomplete. That can keep the statute of limitations from starting. A fix is easier when you catch it early.
Getting the answer right protects you from overpaying and from underreporting.
How the Substantial Presence Test Works in 2026
The test has two parts, and you need to pass both. Think of it as two gates. The first is a short minimum, and the second is the three-year weighted total.
Gate 1: The 31-Day Minimum
You must be physically present in the US for at least 31 days during 2026. If you were here for 30 days or fewer in 2026, you cannot meet the test, however long you stayed in earlier years.
This gate filters out short visitors. A consultant who spent 25 days in the US in 2026 fails here, even after two long prior years.
Gate 2: The Three-Year Weighted Count
If you pass Gate 1, add up your eligible days across three calendar years, weighting each year:
| Calendar Year | Weight | Meaning |
|---|---|---|
| 2026 (current year) | × 1 | Count every eligible day |
| 2025 (first prior year) | × 1/3 | Count one-third of eligible days |
| 2024 (second prior year) | × 1/6 | Count one-sixth of eligible days |
If the total is 183 or more, you meet the Substantial Presence Test, unless an exception applies.
Is 183 Days in One Year Enough?
Not by itself. The 183-day rule you hear about online is a shortcut that confuses two different rules.
You can become a resident with fewer than 183 actual days in 2026, because prior years add weighted days. You can also stay more than 183 days and avoid residency, if you're an exempt individual or qualify for a treaty position.
The practical benchmark is this: steady presence of about 122 days a year for three years produces exactly 183 weighted days. The math is 122 + 40.67 + 20.33 = 183. That figure is a useful warning level for frequent travelers.
The Test in Calculator Form
You can run this calculation by hand, in a spreadsheet, or with a calculator. The method is:
- List your eligible US days for 2026, 2025, and 2024.
- Confirm 2026 days are at least 31.
- Compute: 2026 days + (2025 days ÷ 3) + (2024 days ÷ 6).
- Compare the total to 183.
- Subtract any excluded or exempt days before step 3.
Keep decimals until the final step. Rounding early can push a borderline case the wrong way.
Worked Examples of the Substantial Presence Test
Numbers make the rule real. Here are four common patterns.
Example 1: The Steady Visitor
Priya, a consultant based in Pune, spent 100 days in the US each year in 2024, 2025, and 2026.
- 2026: 100
- 2025: 100 ÷ 3 = 33.33
- 2024: 100 ÷ 6 = 16.67
- Total: 150
She passes Gate 1 but falls short of 183. She is a nonresident for 2026, assuming no other facts apply.
Example 2: The Crossover Case
Daniel, a Canadian engineer, was in the US 140 days in 2026, 120 days in 2025, and 90 days in 2024.
- 2026: 140
- 2025: 120 ÷ 3 = 40
- 2024: 90 ÷ 6 = 15
- Total: 195
He meets the Substantial Presence Test. Unless he qualifies for the closer connection exception or a treaty tie-breaker, he is a resident alien for 2026. Because he was present fewer than 183 actual days in 2026, he may be able to claim the closer connection exception, which we cover below.
Example 3: The New Arrival
Amina arrived on a work visa on March 1, 2026, and stayed through December 31. She had never visited the US before.
- 2026: about 306 days
- 2025: 0
- 2024: 0
- Total: 306
She passes both gates in her first year. Her residency generally begins on her first day of presence in 2026.
Example 4: The F-1 Student
Wei Chen entered the US in August 2024 on an F-1 visa and stayed continuously.
As an exempt individual, his student days are excluded from the count. He remains a nonresident for tax purposes during his exempt period, even though he's physically present nearly every day. He files Form 8843 each year, along with Form 1040-NR if he has US income.
This example matters because students are the most common group who assume the days count and file the wrong forms.
Which Days Count Toward the Presence Test?
The General Rule
You count any day you are physically present in the United States, even for part of the day. Landing at 11:50 pm counts. Departing at 12:10 am counts.
Presence means the 50 states and the District of Columbia. US territories, such as Puerto Rico or Guam, are generally not part of "the United States" for this specific test.
Days You Do Not Count
Several categories are excluded from the day count. These are the ones that most often change a result:
- Commuter days: days you regularly commute to work in the US from a residence in Canada or Mexico.
- Transit days: days you are in the US for less than 24 hours while traveling between two places outside the US.
- Crew days: days you work as a regular crew member of a foreign vessel.
- Medical condition days: days you could not leave the US because of a medical condition that arose while you were here.
- Exempt individual days: days you're an exempt individual, covered in the next section.
Each exclusion has conditions. Claiming one without meeting them is a common error. Publication 519 lists the details.
The Medical Condition Exclusion
A genuine medical emergency can pause your day count. The condition must have arisen while you were in the US, and it must have prevented you from leaving. A planned surgery or a condition that existed before arrival does not qualify.
You report excluded medical days on Form 8843. A statement from your physician is typically needed to support the claim. Keep it with your records.
Exempt Individuals and Visa Categories
An exempt individual is someone whose days the IRS does not count toward the Substantial Presence Test. The term covers specific categories, not everyone on a temporary visa.
Who Qualifies as an Exempt Individual?
Four groups matter most:
- Foreign government-related individuals (typically A and G visas)
- Teachers and trainees on J or Q visas
- Students on F, J, M, or Q visas
- Professional athletes temporarily in the US to compete in a charitable sports event
Time limits apply to the teacher, trainee, and student categories, so the exemption does not last forever.
F-1 and J-1 Students
Students are exempt for a limited number of calendar years. You count calendar years, not school years. A student who arrives in December uses up one calendar year of the exemption almost instantly.
After the exempt period ends, your days start counting. Many students become tax residents in their sixth calendar year, though a longer stay may still be possible if you can show you don't intend to reside permanently in the US and you have complied with your visa terms.
H-1B and L-1 Workers
Workers on H-1B and L-1 visas don't have an exempt status. Every day counts from day one. A worker who arrives early in the year, stays continuously, and passes 183 days becomes a resident alien for that year.
For long assignments, the practical question is rarely "Will I pass the test?" but "When do my residency dates begin and end?" That is the next topic after the exceptions.
The Closer Connection Exception and Form 8840
Meeting the Substantial Presence Test does not always make you a resident. The closer connection exception can keep you a nonresident, and it is the exception people most often misunderstand.
Who Can Claim It?
You must meet all of these conditions:
- You were present in the US for fewer than 183 days in 2026 (actual days, not weighted).
- You maintained a tax home in a foreign country for all of 2026.
- You had a closer connection to that foreign country than to the US.
- You haven't applied for, or taken steps toward, lawful permanent resident status.
That second bullet separates actual days from weighted days. If you were here 183 or more days in 2026, this exception is unavailable.
What Is a Foreign Tax Home?
Your tax home is generally your main place of business or employment, or your regular place of work. It is not necessarily where you sleep or where your family lives. It must be in a foreign country.
A freelancer who works from client sites worldwide and has no fixed base may struggle to prove one. Your tax home evidence decides the claim.
How to Prove a Closer Connection
The IRS looks at your overall life footprint. Evidence that supports a claim includes:
- A permanent home in the foreign country
- Family living there
- A driver's license, bank accounts, and voter registration there
- Your personal belongings, such as furniture and vehicles, being located there
- Social, cultural, and religious ties to that country
No single item decides the claim. A pattern of ties does. Official guidance sits on the IRS page for the closer connection exception.
You claim the exception by filing Form 8840. The filing deadline generally follows your return deadline, and a late filing can forfeit the exception. Check the current instructions before you file.
Tax Treaties and the Tie-Breaker Rules
A US tax treaty can override the Substantial Presence Test result. This applies when you qualify as a resident of both the US and your home country.
Most US income tax treaties include "tie-breaker" provisions. They typically look at where you have a permanent home, where your personal and economic ties are strongest, and your habitual place of abode. If the treaty assigns you to the other country, you may be treated as a nonresident for US tax purposes.
To use this, you generally disclose the position on Form 8833, attached to your return. Not every country has a treaty with the US, and treaty terms differ. The US Treasury's tax treaty resources list the agreements in force.
Closer Connection vs Treaty Tie-Breaker
The two tools solve different problems:
| Feature | Closer Connection Exception | Treaty Tie-Breaker |
|---|---|---|
| Based on | US domestic law | A specific bilateral treaty |
| Requires | Under 183 actual days in the year | Being a resident of both countries |
| Form | Form 8840 | Form 8833 |
| Available to | Many foreign nationals | Only citizens or residents of treaty countries |
Some people qualify for both. Others qualify for neither, so confirm which path applies to you.
Residency Start Date, End Date, and Dual-Status Years
Your residency does not always run for a full calendar year. That produces the dual-status year, where you are a nonresident for part of the year and a resident for the rest.
When Does Residency Start?
Under the Substantial Presence Test, your residency generally starts on the first day you're physically present in the US during the year you meet the test. The IRS allows up to 10 days of nominal presence to be disregarded in some cases if you maintain a closer connection to a foreign country during that period.
When Does Residency End?
Residency generally ends on December 31 of the year you leave. In certain departure cases, it ends on your last day of presence in the US. For that, you must have a closer connection to a foreign country for the rest of the year and not be a resident in the following year.
Dual-Status Returns
In a dual-status year, you file two sets of rules in one filing. The resident portion follows Form 1040 rules, and the nonresident portion follows Form 1040-NR rules. The IRS explains the mechanics in its guidance on dual-status taxation.
Dual-status returns are among the more complex filings in international tax. A professional is worth considering here.
The First-Year Choice
If you don't meet either test in your first year but will meet the Substantial Presence Test in the next year, you may be able to elect resident treatment for part of the first year. The election has specific conditions, including a minimum consecutive-day presence period and a percentage of days present after that period begins. Publication 519 covers the full requirements.
What Happens After You Become a US Tax Resident?
If you're a resident alien, expect these changes:
- Worldwide income is taxable. Foreign wages, foreign rental income, foreign interest, and capital gains abroad all belong on your US return.
- Foreign tax credits may help. If you paid tax abroad on the same income, credits can reduce double taxation. The credit has limits and rules of its own.
- Foreign accounts may trigger reporting. Large foreign bank balances can require separate disclosures. Ask a tax professional about these rules.
- State taxes may apply. Your state of residence has its own rules. See our guide on federal vs state income tax in the USA and the state income tax 2026 overview.
Where you live matters too. Compare states with no income tax in 2026, or review specific pages for Texas, California, and New York.
You can estimate your federal liability with our income tax calculator and your state share with the US state income tax calculator.
Filing as a Nonresident Alien
Nonresidents face a different set of rules, and the income type decides the tax.
Two Types of US Income
- Effectively connected income (ECI): income from a US trade or business, such as wages for work done in the US. It is taxed at graduated rates after allowable deductions.
- Fixed or determinable annual or periodical income (FDAP): passive US-source income, such as dividends and certain royalties. It is generally taxed at a flat 30%, unless a treaty lowers the rate.
Which Forms Do You Need?
- Form 1040-NR: your main nonresident return if you have a filing requirement.
- Form 8843: required for many exempt individuals and for medical-condition exclusions, even with zero US income.
- Form 8840: for the closer connection exception.
- Form 8833: to disclose a treaty-based position.
- Form 4868: to request a filing extension.
Form 8843 vs Form 8840
| Question | Form 8843 | Form 8840 |
|---|---|---|
| Purpose | Excludes days for exempt individuals or medical conditions | Claims the closer connection exception |
| Typical filer | F-1, J-1, and other exempt visa holders | Visitors with under 183 actual days |
| Filed even with no income? | Often yes | Generally yes, if you’re claiming the exception |
| Effect | Keeps excluded days out of the count | Keeps you a nonresident despite passing the test |
Forms 8843 and 8840 do different jobs. Filing the wrong one, or neither, is a frequent and costly mistake.
If you freelance or work remotely for clients abroad while in the US, read our guide to cross-border tax compliance for freelancers. Self-employed residents should also review self-employment tax vs income tax and try the US self-employment tax calculator.
How to Document Your US Presence Days
The IRS tests your day count against records. If you cannot prove your days, an estimate will not hold up.
What to Keep
- Passport stamps and entry and exit pages
- Airline tickets and boarding passes
- Your I-94 arrival and departure record
- Employer travel logs and calendars
- Credit card and bank statements showing location
- Medical records, if you claim the medical exclusion
- Leases, utility bills, and employment letters that prove your foreign tax home
A Simple Day-Count Worksheet
Create one row per trip. Use these columns:
- Entry date
- Exit date
- Total days (count both the entry day and the exit day)
- Excluded days and the reason
- Eligible days
- Calendar year
Then total the eligible days for each year and run the weighted formula. Do this every year, not only when you worry about the result. It also builds a clean record if the IRS later asks questions.
Store scanned copies together. Our guide on how to combine tax documents into one PDF helps you organize them.
Common Mistakes That Lead to Wrong Residency Classification
After reviewing many day-count scenarios, these errors show up again and again:
- Treating 183 days as the only rule. The weighted formula can make you a resident well below 183 actual days.
- Ignoring prior years. The test always looks back at 2025 and 2024, so a quiet 2026 may not save you.
- Counting exempt days. Students and trainees often count days they should exclude.
- Skipping Form 8843. Even with no income, an exempt individual typically needs it.
- Confusing the closer connection exception with the 183-day rule. The exception uses actual days. The test uses weighted days.
- Assuming a visa decides everything. The visa informs your result but doesn't set it.
- Counting days from memory. Without records, you can't defend the count.
- Waiting until after leaving. Residency end dates are easier to document when you plan before your final departure.
For a broader look at what draws IRS attention, read our overview of IRS audit triggers.
US Tax Residency for Different Nationalities and Locations
The Substantial Presence Test is a federal rule, so the US applies the same day-count to everyone. What changes by country is the treaty position and how your home country taxes the same income.
- UK, Canadian, Australian, German, French, Japanese, and Mexican citizens: these countries have income tax treaties with the US, which often include tie-breaker rules. Terms vary, so read the specific treaty.
- Indian and Chinese citizens: treaty provisions can affect students, teachers, and researchers. Check the article that applies to your visa.
- Pakistani citizens: treaty availability and scope differ from other countries, so verify the current position on the Treasury treaty page before relying on any treaty benefit.
- Canada and Mexico commuters: the regular commuter exclusion can apply if you cross the border for work and keep your residence in your home country.
If you also deal with tax obligations at home, compare rules in our tax filing deadlines by country for 2026. Our side hustle taxes 2026 guide helps if you earn on the side, and W-2 vs 1099 tax calculation explains how worker classification changes your bill.
Unfamiliar terms? Our essential tax terms glossary covers the basics.
Why Choose Free Calculator for Your Tax Questions
Tax rules feel less intimidating when the numbers are in front of you. That's the idea behind Free Calculator. We build free tools and guides that turn rules like this one into clear steps.
Here's how we can help:
- Free tools: Explore Advanced Free Calculator tools for income tax, self-employment tax, state tax, and more.
- Clear guides: Our blog library explains tax topics in plain English.
- Transparent methods: We show the formula behind our numbers so you can check them.
- Honest limits: Read our disclaimer to understand what our content can and cannot do.
Our guides are written to inform, and they do not replace advice from a licensed tax professional.
Frequently Asked Questions
What is the Substantial Presence Test for 2026?
The Substantial Presence Test is the IRS day-count rule for deciding if a non-citizen is a US tax resident. In 2026, you must be present at least 31 days in 2026, and your weighted total must reach 183 days. The weighted total is all eligible 2026 days, plus one-third of 2025 days, plus one-sixth of 2024 days.
Is 183 days enough to become a US tax resident?
Not on its own. The rule uses a weighted three-year formula, so you can become a resident with fewer than 183 actual days. You may also avoid residency with more than 183 days if you're an exempt individual or qualify for a treaty position. The closer connection exception, by contrast, requires fewer than 183 actual days in the year.
Do I count the days I arrive and leave the United States?
Yes. Any day you're physically present in the US counts, even if only for part of the day. That includes your arrival day and your departure day. The main exceptions are transit days under 24 hours, commuter days from Canada or Mexico, crew days on foreign vessels, medical-condition days, and exempt-individual days.
Are F-1 students exempt from the Substantial Presence Test?
F-1 students are generally treated as exempt individuals for up to five calendar years, so their days are not counted during that period. They typically file Form 8843 each year, and Form 1040-NR if they have US income. After the exempt period ends, their days begin to count unless an exception applies.
Can I pass the presence test without a green card?
Yes. The Substantial Presence Test and the Green Card Test are separate routes to residency. Many H-1B and L-1 workers meet the Substantial Presence Test without ever holding a green card. Passing the day count can make you a resident alien even without lawful permanent resident status.
Can I remain a nonresident after meeting the test?
Sometimes. The closer connection exception, filed on Form 8840, and a treaty tie-breaker, disclosed on Form 8833, can keep you a nonresident. Each has strict conditions, including a foreign tax home and, for the exception, fewer than 183 actual US days in the year.
Does US tax residency make foreign income taxable?
Yes. Resident aliens are taxed on worldwide income, the same as US citizens. Foreign tax credits and treaty provisions may reduce double taxation, but the income generally must be reported on your US return.
Where can I verify my US tax residency status?
Start with the IRS pages on the Substantial Presence Test and IRS Topic No. 851, then read Publication 519. For a complex case, speak with a licensed international tax professional.
Conclusion:
US tax residency comes down to disciplined counting. Pass the 31-day minimum, reach 183 weighted days, and you're likely a resident unless an exemption or exception applies. Fall short, and you're likely a nonresident.
Here is what to do now:
- Build your day log for 2024, 2025, and 2026 from passport stamps, tickets, and your I-94 record.
- Remove excluded days for exempt-individual status, medical conditions, transit, or commuting.
- Run the weighted formula and keep decimals until the final step.
- Check for exceptions if you land at 183 or above: the closer connection exception, a treaty tie-breaker, or both.
- Identify your forms: Form 8843, Form 8840, Form 8833, Form 1040, or Form 1040-NR.
- Plan before you leave. Your residency end date depends on your records and ties.
Ready to go further? Browse the Free Calculator tools hub, and book a seat at Advance Free Tools offered by Free Calculator to get more from our free tax tools and guides.